British authorities said three people were arrested on October 13, 2026 after a coordinated enforcement operation that targeted what regulators described as a suspected organised group engaged in insider dealing and money laundering. The Financial Conduct Authority led the market-side inquiry with operational support from the National Crime Agency and local police, executing searches at multiple residential addresses in London and Manchester and removing more than 30 mobile phones, laptops and tablets for forensic analysis.
What happened
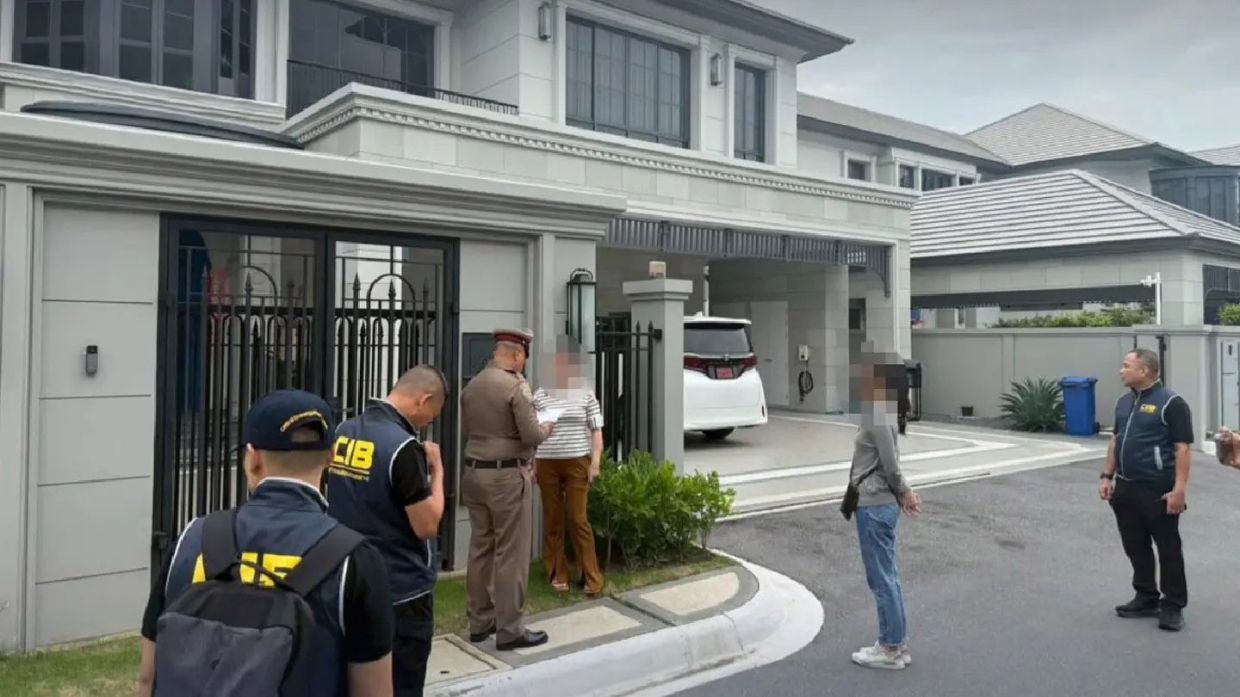
The action on October 13 involved over 100 staff and officers across the investigating agencies, who searched five residential premises and detained three individuals on suspicion of offences related to insider dealing and money laundering. Investigators also seized electronic devices and other material that authorities said could yield digital evidence about trading activity and the movement of illicit proceeds.
How the authorities framed the risk
Regulators treating insider dealing as an organised crime problem rather than isolated misconduct has become a recurring theme in UK enforcement over the past three years. Officials say organised groups can convert confidential, market sensitive information into significant illegal profits, then move those funds through complex channels to conceal their origin. The FCA emphasised the impact insider dealing can have on confidence in UK capital markets, and said it will continue to work with criminal partners to disrupt networks that exploit confidential information for trading advantage.
Why the operation matters to investors and the public
Insider dealing undermines the foundational fairness of financial markets by giving certain actors an unearned edge over ordinary investors. That can distort prices, deter legitimate capital raising, and reduce trust in listed companies and intermediaries. When investigators combine market surveillance, firm cooperation and criminal policing, enforcement can both remove actors responsible for abuse and provide evidence to deter future wrongdoing. The seizures of phones and computers in this operation are intended to give prosecutors the digital trail they need to demonstrate knowledge, communications and fund flows.
Enforcement context and recent trends
The FCA has stepped up enforcement activity on market abuse in recent years, pursuing both civil and criminal pathways against individuals and networks. Criminal prosecutions for insider dealing have produced multi year prison sentences in high profile cases. At the same time, national policing units, including the National Crime Agency and regional organised crime teams, have prioritized economic crime, incorporating financial intelligence and international cooperation where suspects use cross border channels to launder proceeds.
Officials have also emphasised that detection increasingly relies on data driven surveillance, suspicious transaction reporting from firms, and forensic analysis of devices. That layered approach aims to turn signals from market monitoring into criminal investigations when the evidence points to deliberate, organised manipulation or unlawful disclosure of information.
What will happen next
Following arrests under suspicion of insider dealing and money laundering, standard procedure in the UK is active evidence processing by investigators, a charging decision by prosecutors where sufficient admissible evidence exists, and then either summonsing the accused to court or custody while further enquiries continue. The FCA, as the conduct regulator, can also pursue parallel civil or regulatory enforcement, seeking financial penalties and prohibitions against individuals or firms if regulatory contraventions are found.
Because public prosecutions for market abuse require detailed proof that non public information was used or shared to gain trading advantage, the digital material seized during raids will be central to any prosecutorial case. Investigators are likely to run forensic timelines connecting communications, the timing of transactions and subsequent transfers of funds.
Practical implications for market participants
Firms should view operations of this kind as a reminder to maintain robust information barriers, effective surveillance of employee trading and prompt escalation of suspicious internal reports. Continued cooperation between regulated firms and enforcement agencies remains a key source of actionable intelligence. For investors, the visible enforcement posture is intended to protect market integrity and thereby support confidence in price formation and corporate disclosure.
Authorities did not provide further details about the identities of the arrested individuals or the firms, nor did they disclose any alleged target trades or securities. The FCA said it could not comment further at this stage. Prosecutors and police will consider disclosure and charging decisions as the investigation progresses.
While single operations rarely eliminate market abuse, combined regulation and criminal enforcement aim to raise the risk profile for organised actors, making insider dealing a less attractive illicit business model and reducing the harm to ordinary market participants.